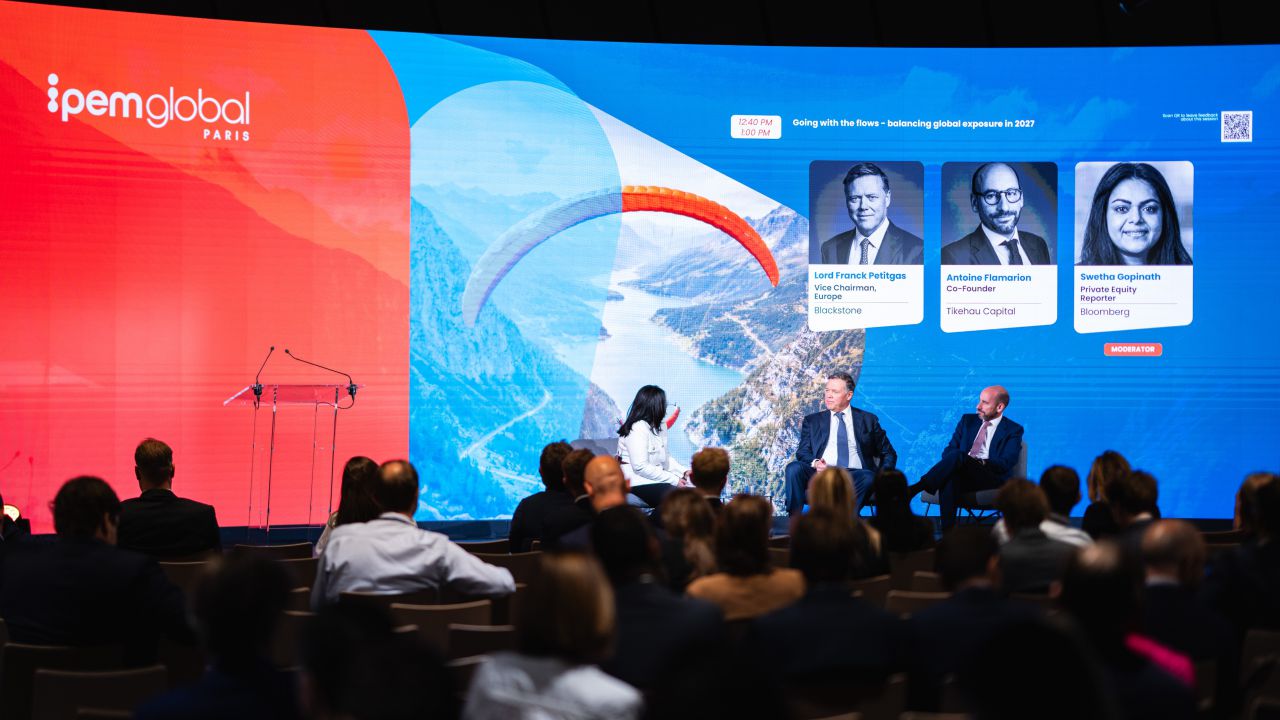
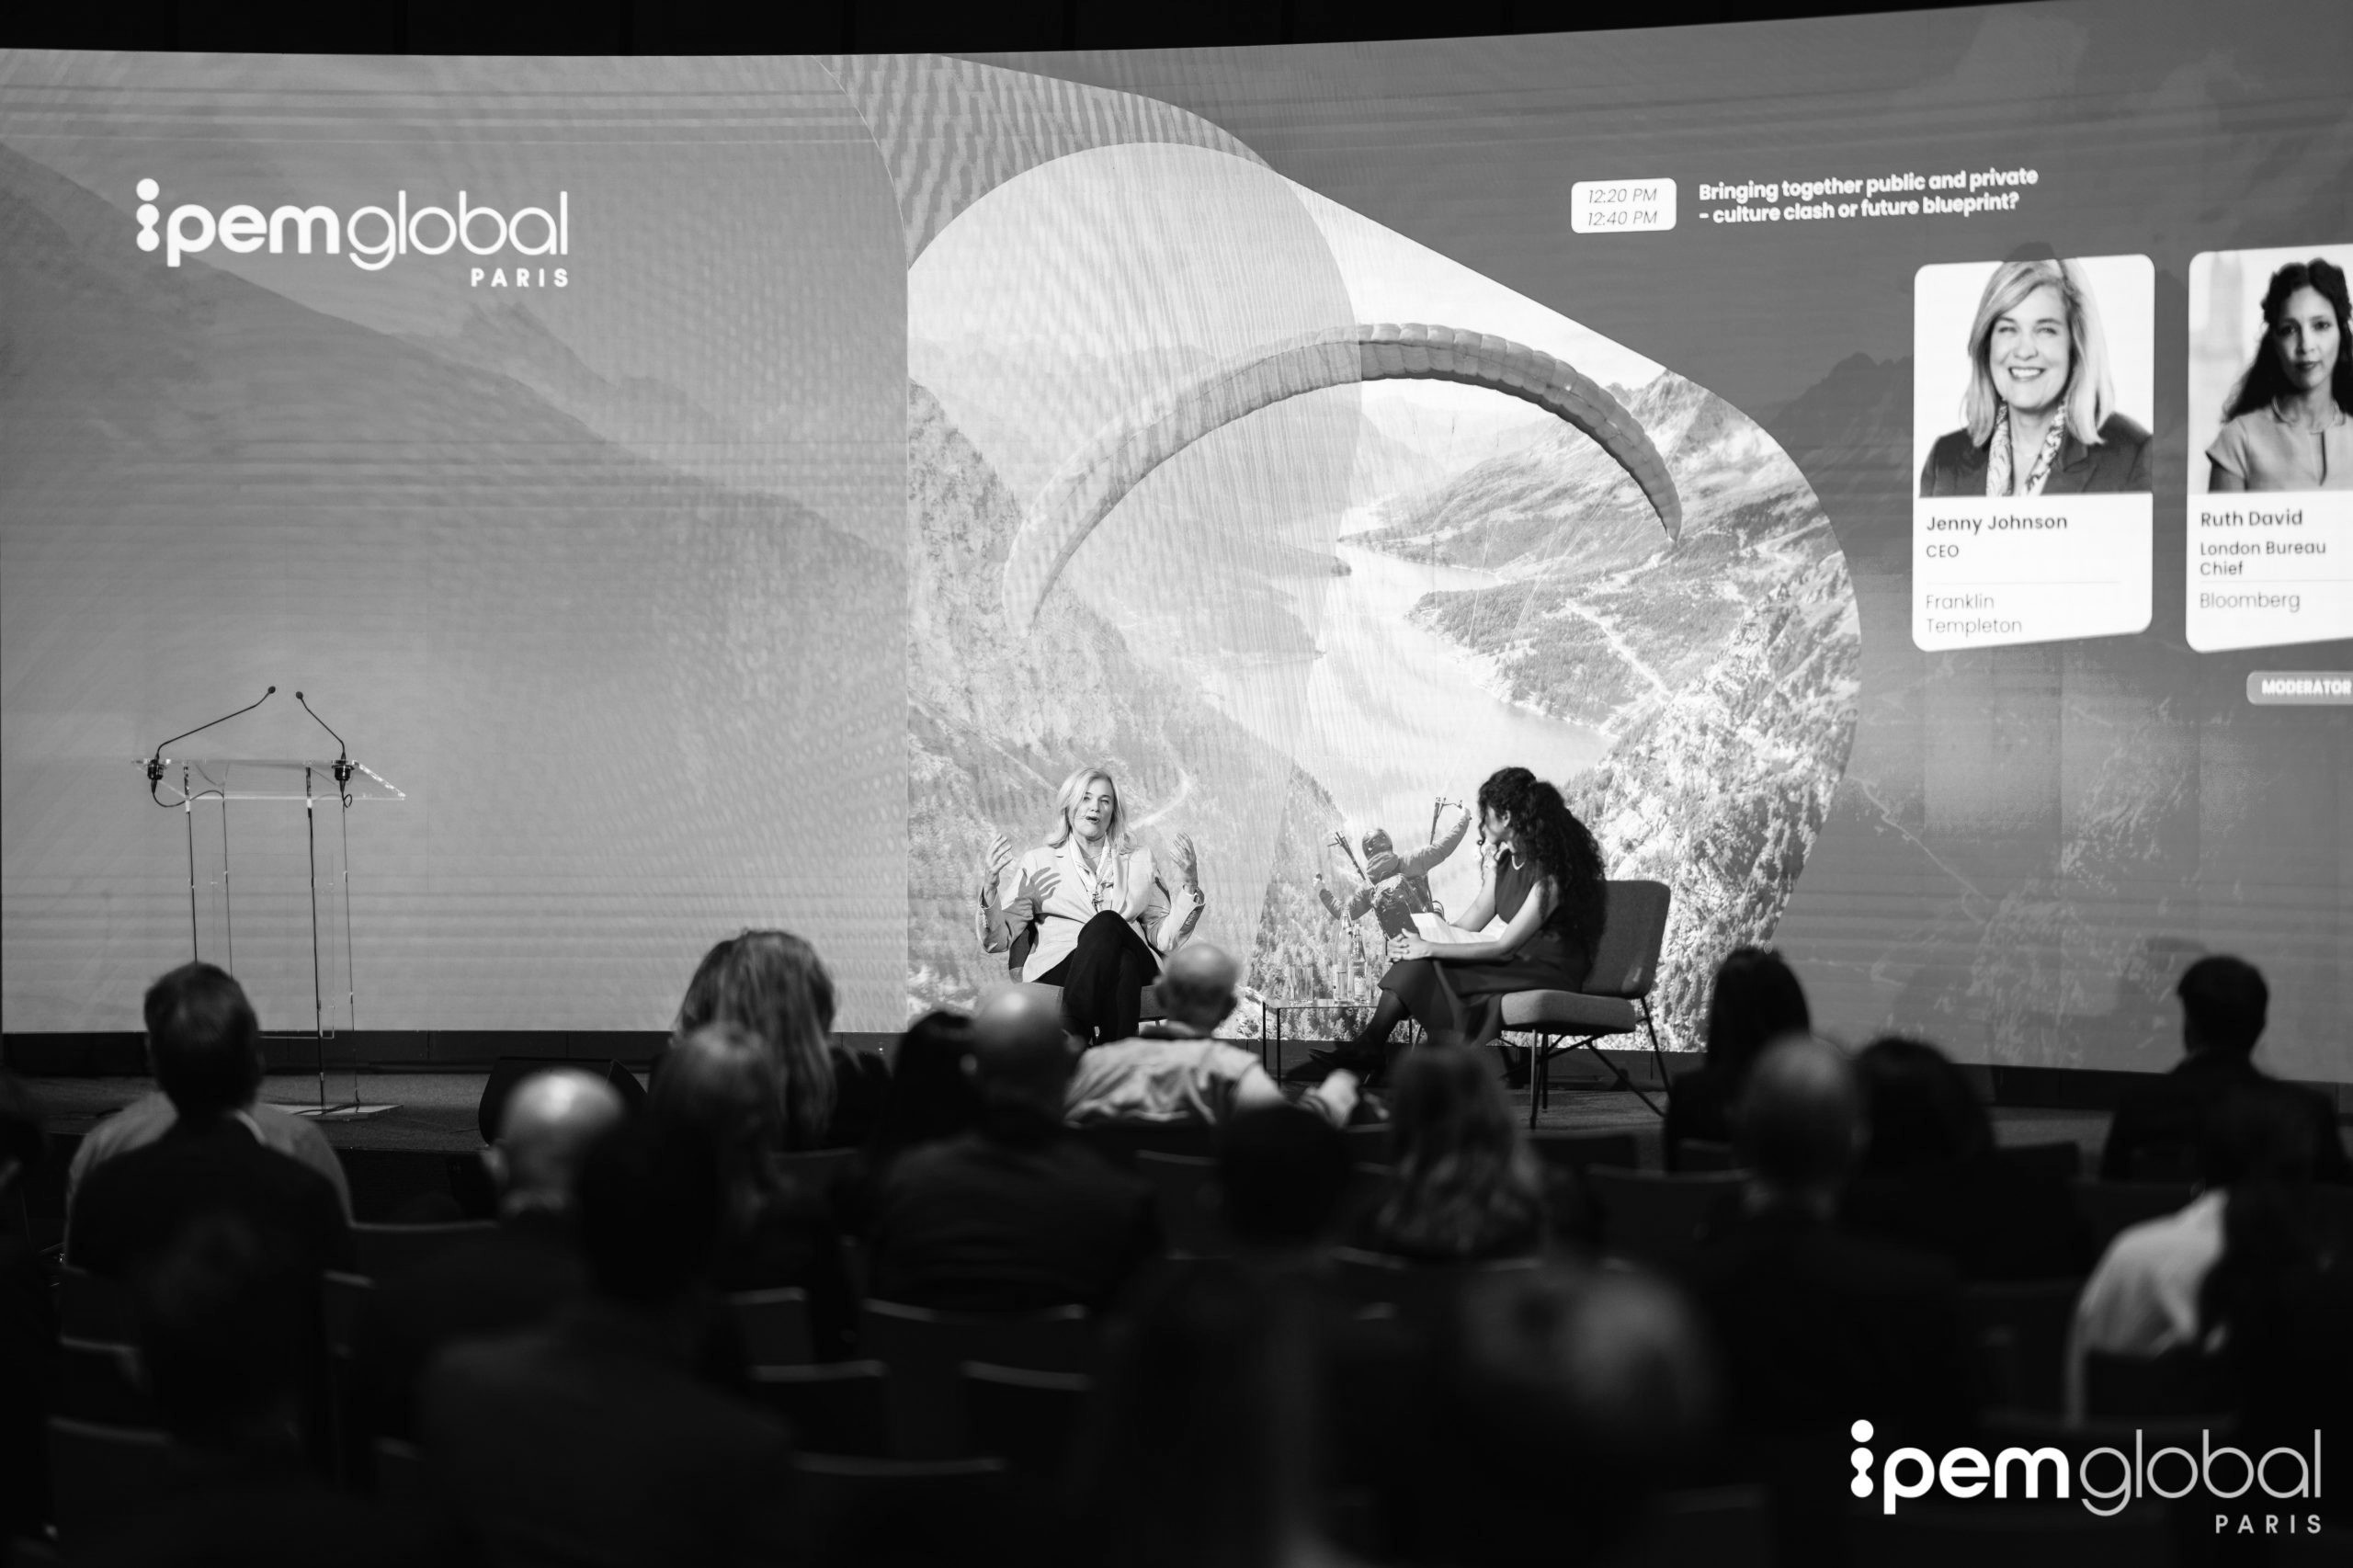
Private markets are becoming an increasingly established component of wealth clients’ portfolios. But broadening access does not mean turning illiquid assets into liquid products. It is precisely this balance — between returns, vehicle structures and investor protection — that has become one of the key challenges for the asset management industry. The issue emerged in Paris during IPEM, at the “Bringing Together Public and Private – Culture Clash or Future Blueprint?” panel, featuring Jenny Johnson, Chief Executive Officer of Franklin Templeton Investments. Johnson’s perspective is that of one of the world’s major asset management groups: Franklin Templeton manages approximately $1.8 trillion and has built a significant presence in private markets in recent years, with assets reaching around $300 billion. The group’s client base is now roughly evenly split between institutional and wealth clients. This gives it a close-up view of the convergence between two worlds that have long remained separate. On the one hand, companies are tending to remain private for longer; on the other, stricter capital requirements have reduced banks’ ability to finance certain segments of the economy, supporting the growth of private credit. For large asset managers, therefore, having a presence across both public and private markets is becoming less and less of an secondary choice.
The real challenge is bringing private markets to wealth clients
The issue, however, is not simply to expand the offering. It is to understand in what form private markets can be incorporated into private clients’ portfolios. Johnson highlighted the illiquidity premium, pointing out how even a relatively modest difference in returns can have a significant impact over the long term. During the panel, she gave an example: an additional 1% annual return, increasing from 7% to 8% and sustained over twenty years, could translate into roughly 20% more wealth at retirement. But precisely for this reason, she explained, the way that exposure is structured and distributed matters. This is driving growing interest in evergreen funds, which seek to provide more flexible access to private assets than traditional drawdown funds. Franklin Templeton currently uses evergreen structures across several segments, from secondary private equity to real estate debt and real estate income. And, Johnson noted, the interest is not coming only from the wealth segment: institutions, foundations, smaller pension funds and insurers are also looking at these vehicles because of the greater predictability they offer in deploying capital. But this is precisely where one of the most delicate issues arises: liquidity. According to Johnson, an evergreen fund should not create the expectation that capital can always be redeemed beyond the limits set by the product. If, for example, the vehicle is structured to provide liquidity of up to 5%, that limit should be considered an integral part of the structure. Consistently exceeding it could give investors the impression that their capital is available at any time. From this perspective, redemption limits are not merely a constraint: they can become a form of protection during periods of market stress, preventing the manager from being forced to sell assets at unfavourable prices to meet concentrated redemption requests.
Accessibility does not mean liquidity
This is certainly one of the most relevant issues for wealth management: making private markets more accessible does not mean eliminating their illiquid nature. The issue becomes even more apparent when moving from institutional investors to private clients. A pension fund or insurance company has a relatively precise understanding of its cash flows and can plan its capital commitments. In wealth management, by contrast, the sustainability of an illiquid investment depends much more on the individual client’s specific circumstances. Johnson emphasised precisely this point: for an adviser, it is not enough to establish that an investment has an attractive risk-return profile. They must also determine whether the client can afford to lock up part of their wealth without needing access to it in the short term. This is where suitability comes into play. Two clients, even with very different levels of wealth, may have opposite capacities to tolerate illiquidity, depending on their standard of living, financial needs and propensity to save. For advisers, therefore, opening private markets to wealth clients brings with it an additional responsibility. And it is no coincidence that Franklin Templeton, Johnson explained, has dedicated over a hundred people to supporting advisers, family offices and smaller institutional investors seeking to increase their exposure to private markets. Educating the distribution network thus becomes an integral part of the product itself.
Private credit, AI and the importance of selection
The discussion then shifted to credit and the impact of artificial intelligence. Johnson urged investors to distinguish between companies with software deeply integrated into their clients’ systems and younger, less established businesses with more fragile cash flows. In the latter case, the risk for lenders can be significantly higher. In private credit, however, Franklin Templeton continues to see solid fundamentals. Johnson reported that around 60% of the companies financed through the group’s direct lending business were performing above the forecasts made at the time of investment. At the same time, investments linked to AI and data centres could create new opportunities on the credit side, particularly when borrowers are large technology companies that are less sensitive to the cost of capital. Selection therefore remains crucial: the sector matters, the borrower matters, and so does the price at which the credit is provided.
Public and private markets, with boundaries becoming increasingly blurred
The picture that emerges is of an industry in which the separation between public and private markets is gradually diminishing. Not because the two worlds have become equivalent, but because an increasing number of investors are seeking to combine them within the same portfolio. For wealth management, however, the issue cannot simply be reduced to the word “democratisation”. The real question is how to broaden access without promising liquidity that the underlying assets cannot provide. And this is where an important part of the next phase of private markets will be decided: not only by the ability to create new vehicles, but by building clear rules, informed distribution and advice tailored to each individual investor.